India Construction Costs Face Energy Price Pressure
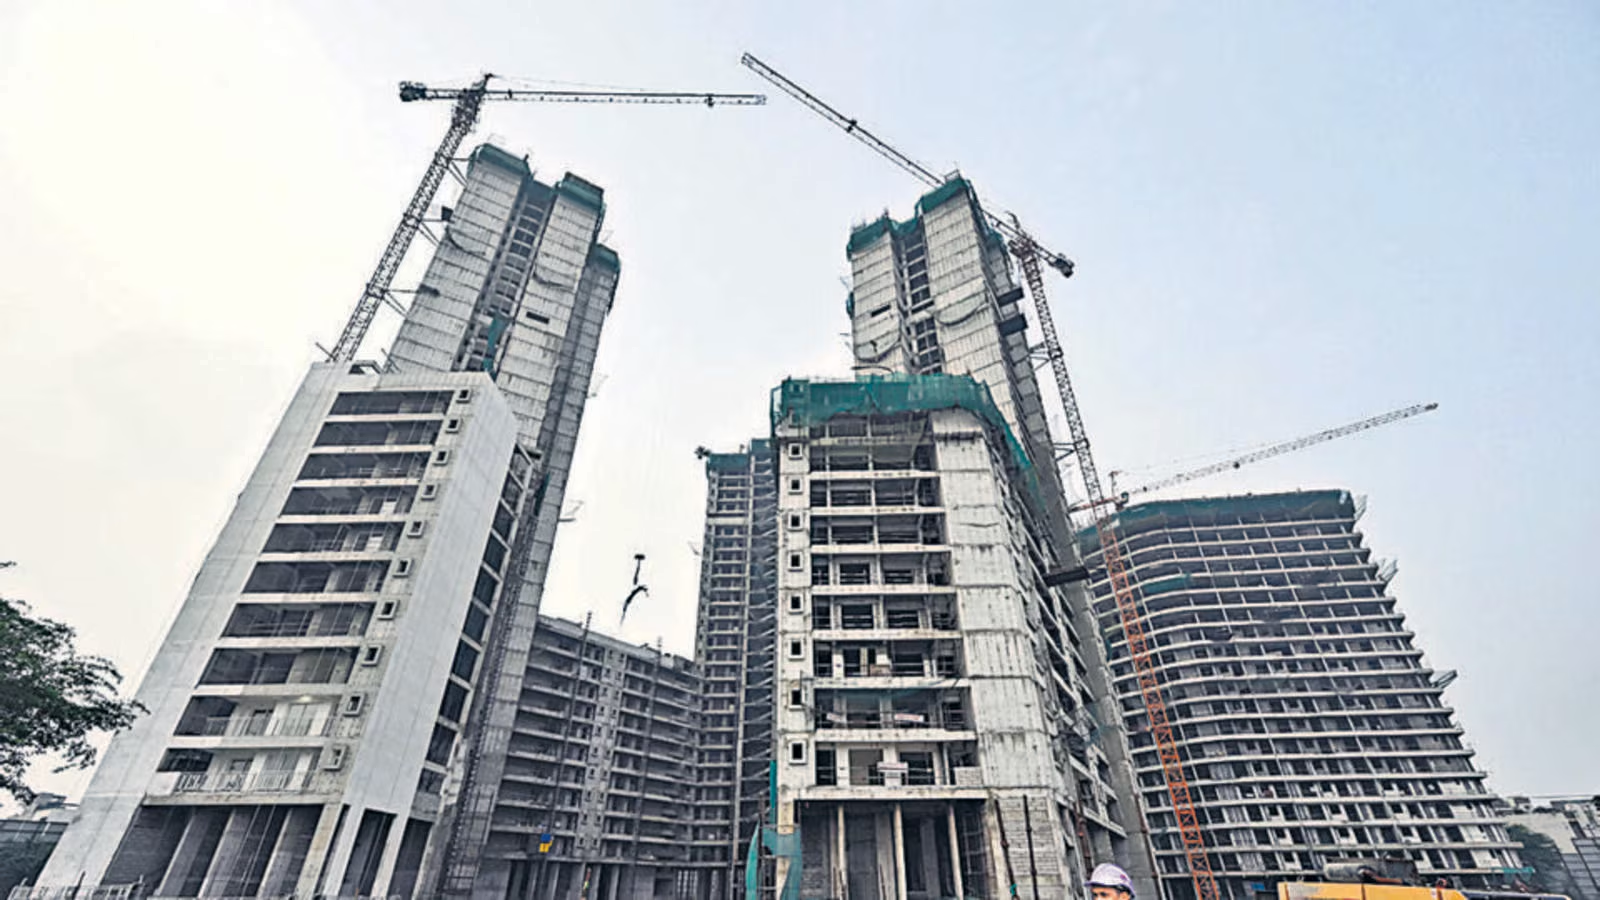
India’s construction and infrastructure sectors could face renewed cost pressures as rising global energy prices and geopolitical tensions in West Asia begin to ripple through building material supply chains. Industry analysts warn that materials widely used in housing, commercial development and infrastructure projects—including steel, aluminium and cement—may become more expensive if energy markets remain volatile.
The concern stems from the sharp rise in global oil prices linked to escalating conflict in the Middle East. Disruptions to energy production and shipping routes in the region have pushed crude prices significantly higher, raising concerns across energy-importing economies such as India. For the construction industry, the impact is particularly significant because many core building materials are highly energy-intensive to manufacture. Cement kilns, steel furnaces and aluminium smelters rely heavily on fossil fuels and electricity to operate. As energy costs climb, production expenses for these materials typically rise as well. Transport costs are another critical factor. Construction materials often move long distances between manufacturing plants, distribution hubs and project sites. Higher diesel prices increase logistics costs across this supply chain, adding further pressure on builders and developers.
Industry experts say the immediate impact in India may be gradual rather than sudden. Many infrastructure and real-estate projects already under construction are tied to fixed procurement contracts that limit short-term price changes. However, if global energy prices remain elevated for several months, future project budgets and new housing launches could begin reflecting higher material costs.Economists are also monitoring broader macroeconomic risks. India imports more than 85% of its crude oil requirements, making its economy sensitive to sustained increases in global energy prices. Any prolonged disruption to energy supply routes—particularly through the Strait of Hormuz—could intensify fuel price volatility and ripple across multiple industrial sectors. For developers and infrastructure planners, this uncertainty adds another layer of complexity to project financing and cost forecasting. Steel, cement and aluminium together represent a substantial share of construction expenditure, meaning even moderate price increases can significantly affect project budgets.
Urban development experts note that the impact could vary across segments. Large government infrastructure projects with long planning horizons may absorb temporary price fluctuations, while smaller private developments—especially housing and commercial construction—could be more sensitive to rising input costs.At the same time, the situation is drawing attention to a deeper structural issue within the construction industry: its heavy reliance on energy-intensive materials. Cement and steel production alone account for a large share of industrial energy consumption and carbon emissions globally. Some planners argue that this volatility may accelerate interest in alternative building materials, energy-efficient manufacturing processes and circular construction practices. These shifts are increasingly seen as essential for building more resilient and climate-aligned urban infrastructure.
For now, developers and contractors across India are closely watching energy markets. If geopolitical tensions continue to push fuel prices higher, the country’s construction sector could soon face another round of cost adjustments that reshape project economics and building timelines.