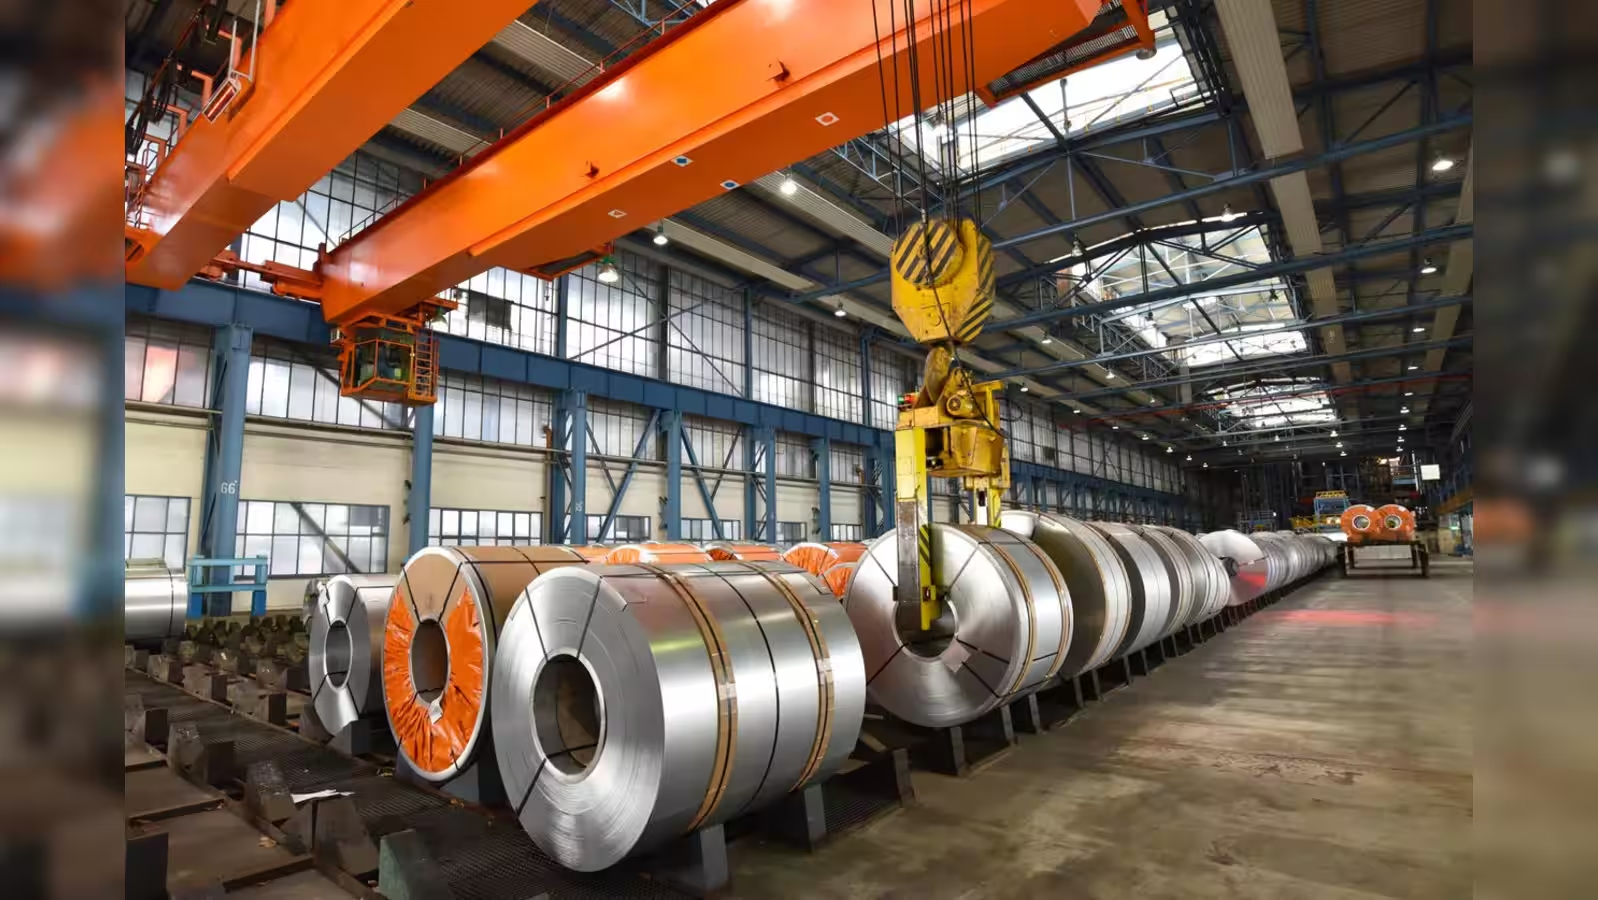
India’s steel market is showing a split pattern across major trading centres, with rebar and billet prices moving in different directions. Mumbai and Mandi recorded gains, while Raipur remained unchanged and Durgapur slipped. The uneven movement matters for construction because steel is a core input for housing, roads and urban infrastructure, making local price changes relevant to project budgets and delivery schedules.
Mumbai rebar prices rose by $3.14 per tonne to about $500 per tonne, equivalent to ₹47,800 per tonne on an ex-works basis. The increase points to some firmness in finished steel demand, although buying remains selective rather than broad-based. Billet, a semi-finished steel product used to manufacture items such as reinforcement bars, also moved differently across markets. Prices in Mandi increased by $2.09 per tonne to ₹43,200 per tonne on a delivered basis. In Raipur, billet prices held at ₹39,600 per tonne, while Durgapur recorded a modest decline of $1.05 per tonne to ₹40,200 per tonne. The divergence suggests that India steel prices are being shaped by local trading conditions rather than a uniform national demand cycle. Transport costs, inventory levels, mill availability and regional construction activity can all influence what buyers are willing to pay. For developers and contractors, that makes procurement planning more important, particularly when projects operate on tightly controlled budgets.
The impact extends beyond the steel trade. Higher reinforcement costs can increase construction expenses for residential buildings, commercial projects and public infrastructure if price increases persist. For homebuyers, the effect may not immediately appear in property prices, but sustained increases in construction inputs can influence project feasibility and future pricing decisions. RERA-registered projects also have a particular need for cost discipline. The Real Estate (Regulation and Development) framework requires developers to provide greater transparency around project commitments, making unexpected input-cost movements an important consideration in financial planning. However, a short-term rise in steel prices does not automatically translate into higher property prices or changes in RERA obligations.
The current market therefore offers a mixed signal rather than a clear upward trend. Moderate demand and selective purchasing could limit further price gains, while stronger infrastructure and construction activity could provide support if buying improves. For cities expanding housing, transport networks and essential infrastructure, the next phase of steel pricing will be important. Stable input markets can help projects remain financially predictable, while sharp regional swings may require closer procurement monitoring to protect construction timelines and affordability.